EVENT DESCRIPTION
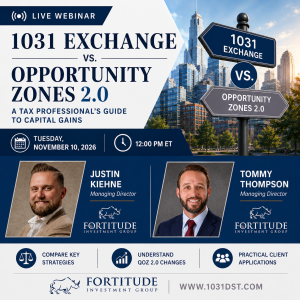
The One Big Beautiful Bill Act significantly reshaped the Qualified Opportunity Zone program beginning in 2027, creating new planning opportunities for taxpayers realizing capital gains. This session compares the updated Opportunity Zone rules with Section 1031 exchanges and explores when each strategy may be appropriate.
Attendees will review the key mechanics, timelines, and tax benefits of each strategy; the major changes introduced under QOZ 2.0; and practical client scenarios involving real estate sales, business interests, securities, and pass-through entities.
EVENT OBJECTIVE
Upon completion of this program, participants will be able to:
1. Explain the major provisions of Qualified Opportunity Zones 2.0, including the new five-year gain-deferral framework, basis adjustments, 10-year appreciation exclusion, and enhanced incentives for qualifying rural Opportunity Zone investments.
2. Compare Section 1031 exchanges and Qualified Opportunity Fund investments, including differences in eligible assets, reinvestment requirements, deadlines, tax-deferral periods, and long-term tax treatment.
3. Identify client situations in which a 1031 exchange, DST replacement property, or Qualified Opportunity Fund may warrant further evaluation, including appreciated real estate sales, business and securities gains, pass-through entity gains, and clients seeking greater liquidity or passive ownership.